Serving Pennsylvania, New Jersey, and Delaware
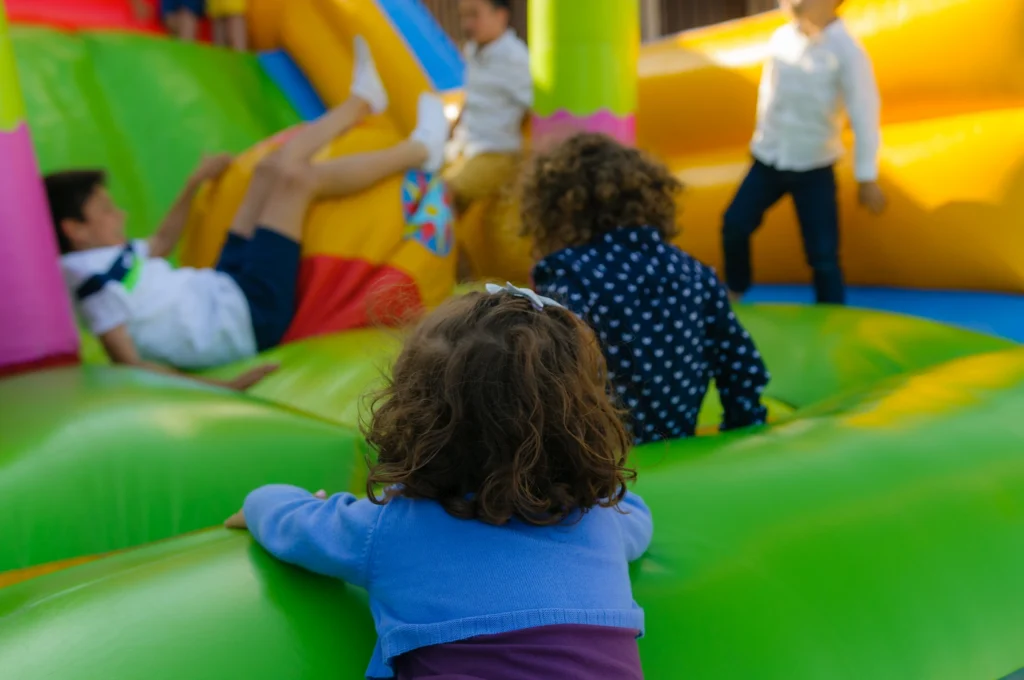
Children playing inside a bounce house representing personal liability coverage for homeowners

If Someone Were Injured at Your Home Today, Would Your Insurance Be Enough?

A backyard birthday party. Kids playing on a bounce house. Friends gathered around a firepit. A delivery driver walking up your front steps.

These are ordinary moments at home—but it only takes one unexpected accident for an enjoyable day to turn into a serious financial concern.

Most homeowners know their insurance protects the house itself. What is often less understood is how a homeowners policy may respond when someone else is injured on the property.

If it happened today, would you know what your coverage provides?

Accidents at Home Are Not Always About the House

When people think about homeowners insurance, they often picture fires, storms, theft, or damage to the physical structure. However, a typical homeowners policy may also include personal liability coverage for certain injuries or property damage for which the policyholder is found legally responsible.

Imagine that:

  • A guest trips on an uneven walkway
  • A child is injured while playing in your yard
  • A visitor slips near your swimming pool
  • Your dog bites a neighbor
  • A tree from your property damages someone else’s belongings
  • A guest falls down your basement stairs
  • Someone is injured during a party or family gathering

Whether and how a policy responds depends on the circumstances, the language of the policy, applicable exclusions, and the limits you selected.

That is why it is important to understand your coverage before an accident occurs—not while you are already dealing with one.

What Is Personal Liability Coverage?

Personal liability coverage is generally included as part of a homeowners insurance policy. It may help protect you financially if you are found legally responsible for bodily injury or property damage involving someone else. Depending on the policy and circumstances, this coverage may help pay for:
  • The injured person’s medical expenses
  • Lost wages resulting from the injury
  • Legal defense expenses
  • Settlements
  • Court judgments
  • Damage to another person’s property
Coverage is subject to the terms, exclusions, and liability limit shown on the policy. Once that limit has been exhausted, additional expenses may become your responsibility. The National Association of Insurance Commissioners notes that personal liability coverage addresses covered financial losses involving injuries or property damage to others when the homeowner is found legally responsible.

What Are Medical Payments to Others?

Homeowners policies may also include a separate coverage commonly called medical payments to others.

This coverage can help pay smaller medical expenses when a guest is accidentally injured on your property, regardless of who was at fault, subject to the policy’s terms and limits. It may apply to expenses such as an ambulance ride, X-rays, an emergency room visit, or other necessary treatment.

Medical payments coverage is different from personal liability coverage. It typically has a much lower limit and is intended for relatively minor injuries—not significant claims, lawsuits, or injuries involving members of your household.

Although the two coverages may appear next to each other on your policy, they serve different purposes.

Does Homeowners Insurance Cover Every Injury?

No. Having homeowners insurance does not mean every accident or injury will automatically be covered.

Policies commonly contain exclusions, limitations, and conditions that affect how coverage applies. Issues may arise when an injury involves:

  • An intentional act
  • A business operated from the home
  • Certain vehicles
  • Undisclosed property features
  • Certain animals or dog breeds
  • Pools, trampolines, or other recreational equipment
  • A rental or short-term rental arrangement
  • Activities specifically excluded by the policy

Coverage can also vary significantly between insurance companies and policy forms.

For example, owning a bounce house, trampoline, swimming pool, or similar recreational feature does not automatically mean you have no coverage. However, your insurance company may need to know about it, may require certain safety measures, or may place specific conditions or exclusions on the policy.

The safest approach is to ask rather than assume.

Are Your Liability Limits High Enough?

Even when an incident is covered, the liability limit on the policy still matters.

Medical care, legal representation, settlements, and judgments can become expensive quickly when an injury is serious. A liability limit chosen years ago may no longer provide the level of protection you expect today.

When evaluating your limit, consider more than the value of your home. Think about your broader financial picture, including:

  • Savings
  • Income
  • Investments
  • Property
  • Future earnings
  • The frequency with which you host guests
  • Features that may increase activity or risk at your home

The goal is not to predict every possible accident. It is to determine whether your current coverage offers reasonable protection if a significant claim occurs.

When Does an Umbrella Policy Help?

A personal umbrella policy provides additional liability protection above the limits of certain underlying policies, such as homeowners and auto insurance.

For example, if a covered liability claim exceeds the limit on your homeowners policy, an umbrella policy may provide additional coverage after the underlying limit has been reached, subject to the umbrella policy’s own terms and exclusions.

Umbrella coverage may be worth discussing if you:

  • Own a home or rental property
  • Have substantial savings or other assets
  • Have a pool, trampoline, or recreational equipment
  • Frequently host guests
  • Own a dog
  • Have teenage drivers
  • Volunteer, coach, or serve on a board
  • Want additional protection against a major liability claim

You do not necessarily need to consider yourself wealthy to face a costly lawsuit. Your income and future earnings may also be part of your overall exposure.

Small Steps Can Help Reduce the Risk

Insurance provides financial protection, but preventing injuries is always the better outcome.

Walk through your property as though you were visiting it for the first time. Look for conditions that could create problems, including:

  • Loose railings
  • Uneven walkways
  • Poor exterior lighting
  • Slippery steps
  • Unsecured rugs
  • Unlocked pool gates
  • Damaged play equipment
  • Overgrown branches
  • Unrestrained pets
  • Extension cords or clutter in walking areas

If you are hosting a gathering, take a few minutes to check the areas guests will use. Make sure recreational equipment is properly secured and supervised, walkways are clear, and potentially dangerous areas are inaccessible to children.

These steps cannot prevent every accident, but they can make your home safer for everyone who visits.

If It Happened Today, Would You Be Ready?

You cannot anticipate every slip, fall, bite, collision, or backyard mishap. You can, however, understand the protection you currently have.

Reviewing your homeowners liability limits, medical payments coverage, exclusions, and umbrella options can help you make informed decisions before an accident puts that coverage to the test.

At Sablich Insurance Group, we help homeowners understand what their policies actually provide, identify areas that deserve a closer look, and consider coverage that reflects their home, lifestyle, and financial situation.

Raise Your Expectations.

If you are unsure whether your current liability coverage would be enough after a serious accident, contact our team for a coverage review and personalized guidance.

Sablich Insurance Group is licensed in Pennsylvania, New Jersey, and Delaware.

Scroll to Top
Skip to content